Hospitality Newsletter
Latest trends of the Greek hospitality sector
Explore Newsletters
The GBR Consulting Hospitality Newsletters provide a snapshot of the performance and outlook of the Greek hotel industry, within the broader context of the international hospitality industry as well as of Greek tourism and Greek socio-economic developments.
Greek Hospitality Industry Performance - 3rd Quarter 2026
International tourism remains on a growth trajectory
According to the Bank of Greece, inbound traveller flows increased by 10.0% and travel receipts (excluding cruises) by 9.7% YTD August 2026. Growth varied considerably across source markets, with arrivals from Italy (+22.1%) and Germany (+8.1%) outperforming, while arrivals from France (-5.4%) and the United States (-1.5%) declined.
Visitor expenditure trends differed significantly across source markets. The United States recorded a 21.0% increase in travel receipts despite a 1.5% decline in arrivals, accompanied by a substantial 22.8% increase in average expenditure per trip. Italy performed particularly strongly, with arrivals increasing by 22.1%, receipts by 31.7% and expenditure per trip by 7.9%. In contrast, German receipts increased by 7.2%, slightly below the 8.1% growth in arrivals, while France recorded declines in both arrivals (-5.4%) and receipts (-8.1%). Overall, average expenditure per trip remained virtually unchanged (-0.3%), indicating that growth in tourism receipts was largely driven by higher visitor volumes.
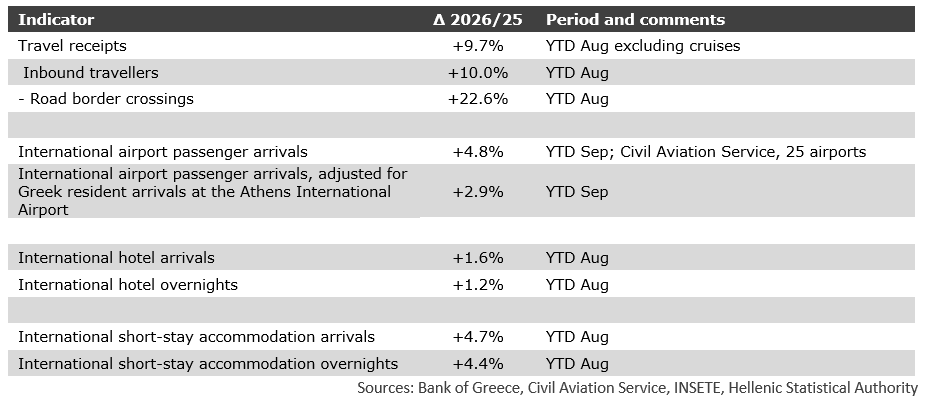
Road tourism continues to drive a significant part of the increase in visitor flows. Inbound travellers through road border crossings increased by 22.6%, substantially outpacing air arrivals. This partly explains why the strong growth in international visitor flows has not translated into equivalent increases in registered accommodation demand. International hotel arrivals and overnight stays increased by only 1.6% and 1.2%, respectively YTD August.
International airport passenger traffic increased moderately, with substantial differences between destinations. Across Greece's 25 international airports, international passenger traffic increased by 4.8% through September, or approximately 2.9% when adjusting for Greek resident arrivals at Athens International Airport. The ten largest airports accounted for approximately 93% of international passenger traffic and recorded combined growth of 4.5%. Mykonos (+8.0%), Chania (+9.5%) and Corfu (+7.0%) performed particularly well, while Kos and Santorini recorded broadly stable international traffic. However, domestic passenger traffic increased by 8.9% at the Santorini airport, highlighting the importance of domestic air connections, including for international visitors travelling via Athens.
Short-stay accommodation continues to record growth. According to ELSTAT, international arrivals and overnight stays at short-stay accommodation establishments increased by 4.7% and 4.4%, respectively, through August 2026. Separately, ELSTAT's experimental statistics on platform-based short-term rentals recorded 8.65 million days of lease in 2025, an increase of 4.7% over 2024, with non-residents accounting for 84.8% of the total.
Short-term rentals represent a significant component of Greece's accommodation market. According to AADE, declared rental income reached approximately €974 million in 2025, equivalent to around 8% of the estimated €12.5 billion turnover generated by Greek hotels, as reported by the Hellenic Chamber of Hotels. The proportion would be higher if compared with hotel room revenue alone. The Hellenic Statistical Authority recorded approximately 203,000 properties in the Short-Term Stay Property Registry as of March 2026, while tighter regulations and restrictions on new registrations in certain areas may constrain future supply growth.
Athens – strong rate growth continues amid stable occupancy
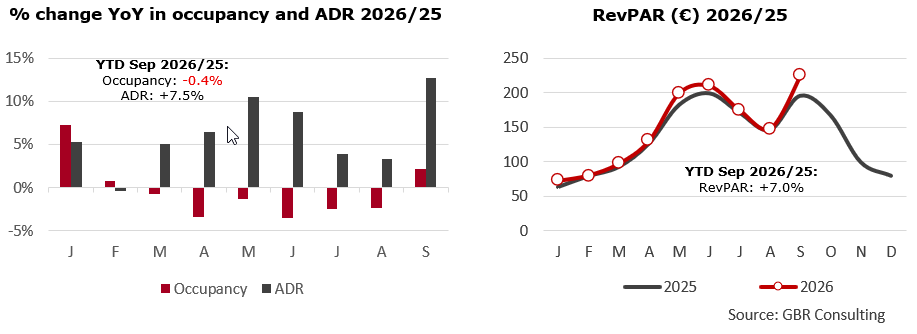
Athens hotels maintained strong operating performance through September 2026, with revenue growth driven primarily by higher room rates. YTD occupancy remained broadly stable at 77% (-0.4%), while ADR increased by 7.5% to €195, resulting in a 7.0% increase in RevPAR to €151.
Performance strengthened considerably in September, with RevPAR increasing by 15.1%, following relatively modest growth in July and August (+1.4% and +0.9%, respectively).
Thessaloniki - Modest RevPAR growth despite higher room rates
Thessaloniki hotels recorded modest RevPAR growth through September 2026. YTD occupancy declined by 1.4% to 69%, while ADR increased by 4.4% to €111, resulting in a 2.9% increase in RevPAR to €76.
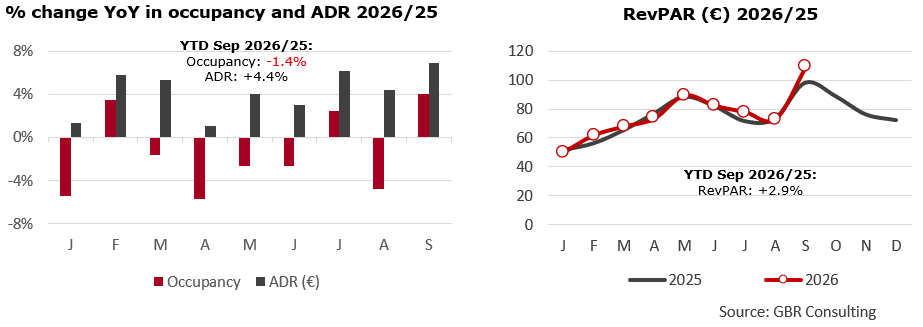
Performance improved significantly in September, following mixed results during the summer months. Occupancy increased to 84% in September 2026, while ADR rose by 6.9%, resulting in RevPAR growth of 11.3%.
Resort hotels - strong revenue growth amid stable occupancy
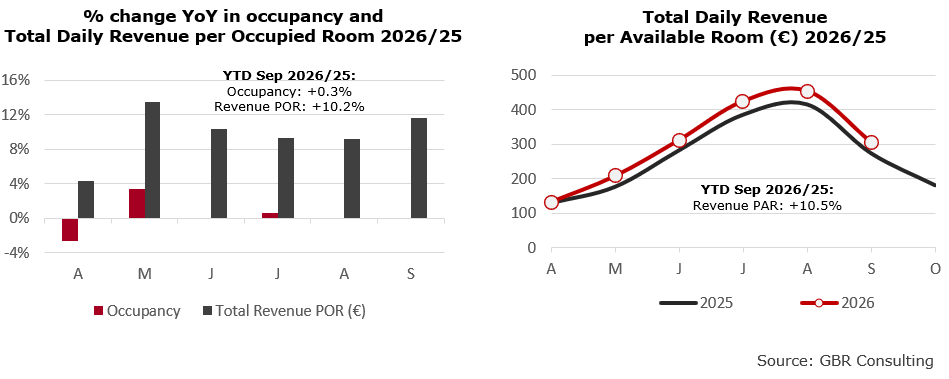
Resort hotels maintained strong operating performance through September 2026. YTD occupancy remained stable at 86% (+0.3%), while Total Daily Revenue per Occupied Room increased by 10.2% to €371, resulting in a 10.5% increase in Total Daily Revenue per Available Room to €318.
Revenue growth remained consistently strong throughout the main summer season, with Total Daily Revenue per Available Room increasing by 10.3% in June, 9.9% in July, 9.2% in August and 11.5% in September. Total revenue increased by 12.9% YTD, reflecting sustained revenue growth despite limited changes in occupancy.
Hotel chain landscape 2026
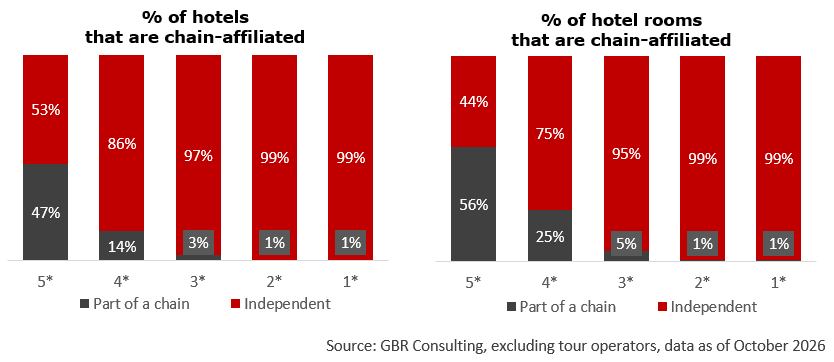
As of October 2026, 8% of all hotels and 23% of hotel rooms in Greece are part of an international, national or local hotel chain, defined as a group of two or more hotels operating under a common brand identity visible to the guest. Some companies operate multiple hotels, but if the properties do not share a brand that is presented to the guest, they are not classified as a branded hotel chain. Tour operators are excluded from this analysis.
For the purpose of this report, an international chain operates in two or more countries, a national chain operates only in Greece, and a local chain operates exclusively within a specific city, island, or defined local area, under a common brand.
Compared to October last year, we note overall a small increase in penetration both in hotels and rooms. However, most changes are recorded among international chains in Greece.
International hotel brands expand further, led by luxury properties
International hotel chains continued to expand their presence in Greece between October 2025 and October 2026. The number of hotels affiliated with at least one international hotel brand increased from 352 to 402 (+14.2%), while room capacity grew from 32,733 to 36,834 rooms (+12.5%). Tour operators are excluded from this analysis.
Luxury hotels are driving the expansion. The 5-star hotels accounted for 28 of the 50 additional internationally branded hotels and 3,459 of the 4,101 additional rooms. The internationally branded 5-star segment reached 217 hotels and 27,128 rooms in October 2026, compared with 189 hotels and 23,669 rooms a year earlier. International chains now account for 25% of all 5-star hotels and 24% of 5-star hotel rooms in Greece.
International brand penetration remains limited outside the luxury segment. In the 4-star category, the number of internationally branded hotels increased from 67 to 70, representing just 4% of total 4-star hotel stock. In the 1 to 3-star categories, only 18 hotels are affiliated with an international hotel chain.
A total of 40 international hotel chains are now present in Greece, representing 439 hotels and non-hotel accommodation establishments with 41,029 rooms. Of these, 37 establishments with 4,195 rooms are non-hotel accommodation, while the remaining 402 hotels account for 36,834 rooms.
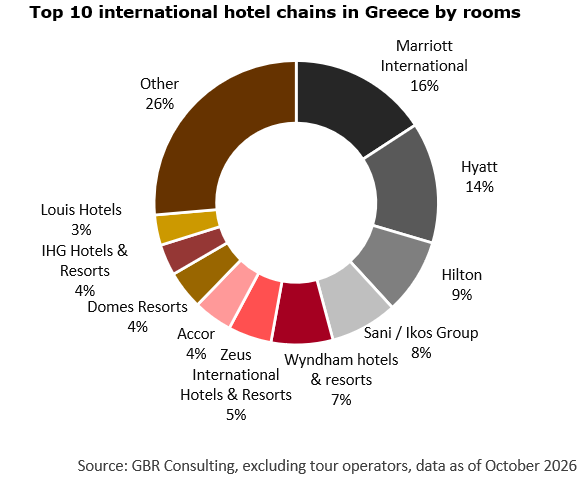
The leading international hotel chains have maintained their positions. Compared with October 2025, the six largest chains retained their rankings, led by Marriott Hotels, Hyatt Hotels and Hilton Hotels & Resorts. Accor moved from ninth to seventh place, overtaking Louis Hotels, which dropped in the opposite direction. Properties affiliated with multiple brands or hotel groups are counted separately under each affiliation, resulting in some double counting.
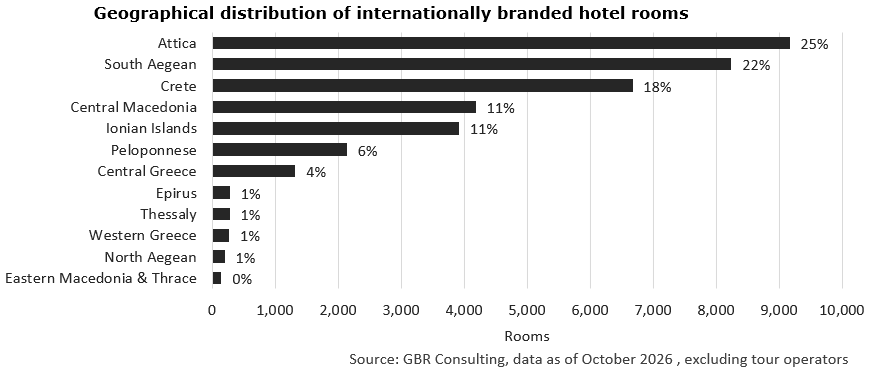
Internationally branded hotel supply remains concentrated in a limited number of regions. Attica accounts for the largest share of rooms (25%), followed by the South Aegean (22%) and Crete (18%). Together, these three regions represent 65% of internationally branded hotel room capacity. Central Macedonia and the Ionian Islands account for a further 11% each, bringing the combined share of the five leading regions to 87%. Brand penetration in the remaining regions is considerably more limited, while Western Macedonia has no internationally branded hotels.
Selected investment activity
Since 2023, PRODEA Investments has progressively consolidated its hospitality investments under MHV Mediterranean Hospitality Venture, with the objective of establishing a dedicated hospitality investment and development platform. PRODEA increased its participation in MHV from 25% to approximately 80% in early 2024 and subsequently to 99.99% in April 2025. MHV has become the group's principal hospitality investment vehicle, combining hotel investments, redevelopment projects and complementary real estate developments.
In October 2026, MHV announced the addition of the 201-room Moxy Athens City to its hospitality portfolio. The hotel operates under a long-term lease held by Rinascita S.A., which PRODEA had acquired in December 2025 and subsequently transferred to MHV in March 2026. The development therefore forms part of the group's internal consolidation of hospitality investments.
Meanwhile, Nikki Beach Resort & Spa Porto Heli, already part of the MHV portfolio, has closed for an extensive renovation and repositioning. The property is scheduled to reopen on 1 June 2027 as Aliis Resort Porto Heli – MGallery Collection, part of Accor's international portfolio. The repositioned beachfront hotel will feature 65 rooms and suites, including accommodation with private pools, rooftop Jacuzzis and terraces overlooking Porto Heli Bay.
MHV's hospitality portfolio includes Parklane in Limassol, The Landmark Nicosia, Nikki Beach Porto Heli, Moxy Athens City and the Porto Paros redevelopment project. Its investments also extend to the Bellevue Hotel in Cortina d'Ampezzo, Italy, Ergon House at Mitropoleos 23 in Athens, and a planned 37-room five-star hotel at Mitropoleos Square. Outside MHV, PRODEA retains additional hospitality investments, including its 49% participation in V Tourism, owner of White Coast on Milos, hotel properties leased to third-party operators such as Lazart Hotel in Thessaloniki and Moxy Patra Marina, and hotel-related properties and developments in Cyprus, including Aphrodite Hills, Pernera and Nicosia.
Chandris Hotels announced in September 2026 an agreement to acquire Milos Cove Inception Resort, a 5-star luxury resort on the island of Milos, through the acquisition of shares in the owning company for €17 million. The property comprises 42 suites and villas, with an approved expansion of 17 additional accommodation units. Developed by the Kolitsis family between 2015 and 2019, the resort opened in June 2018 while parts of the property were still under construction.
In September 2026, Highgate, a US-based hotel investment and management company, together with French asset manager Eternam, acquired the Athens Zafolia Hotel, a 4-star, 191-room property on Alexandras Avenue in Athens, through the acquisition of 100% of the shares in the hotel-owning company. The transaction marks Highgate's first hotel investment in Greece. Highgate will also assume management of the property, with plans for an extensive renovation and rebranding under an international hotel franchise. The acquisition price was not officially disclosed, although Greek media reported a consideration exceeding €30 million.
In September 2026, Marbella S.A., owner of Mar-Bella Collection, acquired Cayo Creta S.A., the owner and operator of the Cayo Exclusive Resort & Spa, a 5-star luxury resort in Plaka, Elounda, Crete. The property comprises 117 rooms, suites and villas, most with private pools, overlooking Spinalonga. The acquisition marks Mar-Bella Collection's entry into Crete, expanding its portfolio to five luxury resorts. The acquisition price was not disclosed.
Bank lending to hospitality businesses increases, driven by large enterprises
Bank lending to accommodation and food-service businesses increased significantly during 2026. According to the Bank of Greece's AnaCredit statistics on new loans by economic activity and enterprise size, new lending reached €748 million during January – August 2026, an increase of 18% compared with the same period in 2025 and 28% compared with 2023.
Growth was concentrated among large enterprises, with new lending increasing by 95% to €348 million, while lending to SMEs declined by 13% to €400 million. Large enterprises accounted for 47% of new lending through August 2026, compared with 28% in 2025 and 17% in 2023, indicating a substantial shift in the distribution of bank financing towards larger businesses. The published data do not provide a regional breakdown of lending.
Download in PDF format (337 kb)